11 October 2026·7 min read·Filed under NRI & Foreign Income·RNOR / NRI / Residential Status / Section 6 / Returning NRI
RNOR: The Third Residence Status, and the Two-to-Three Year Window Returning NRIs Keep Missing
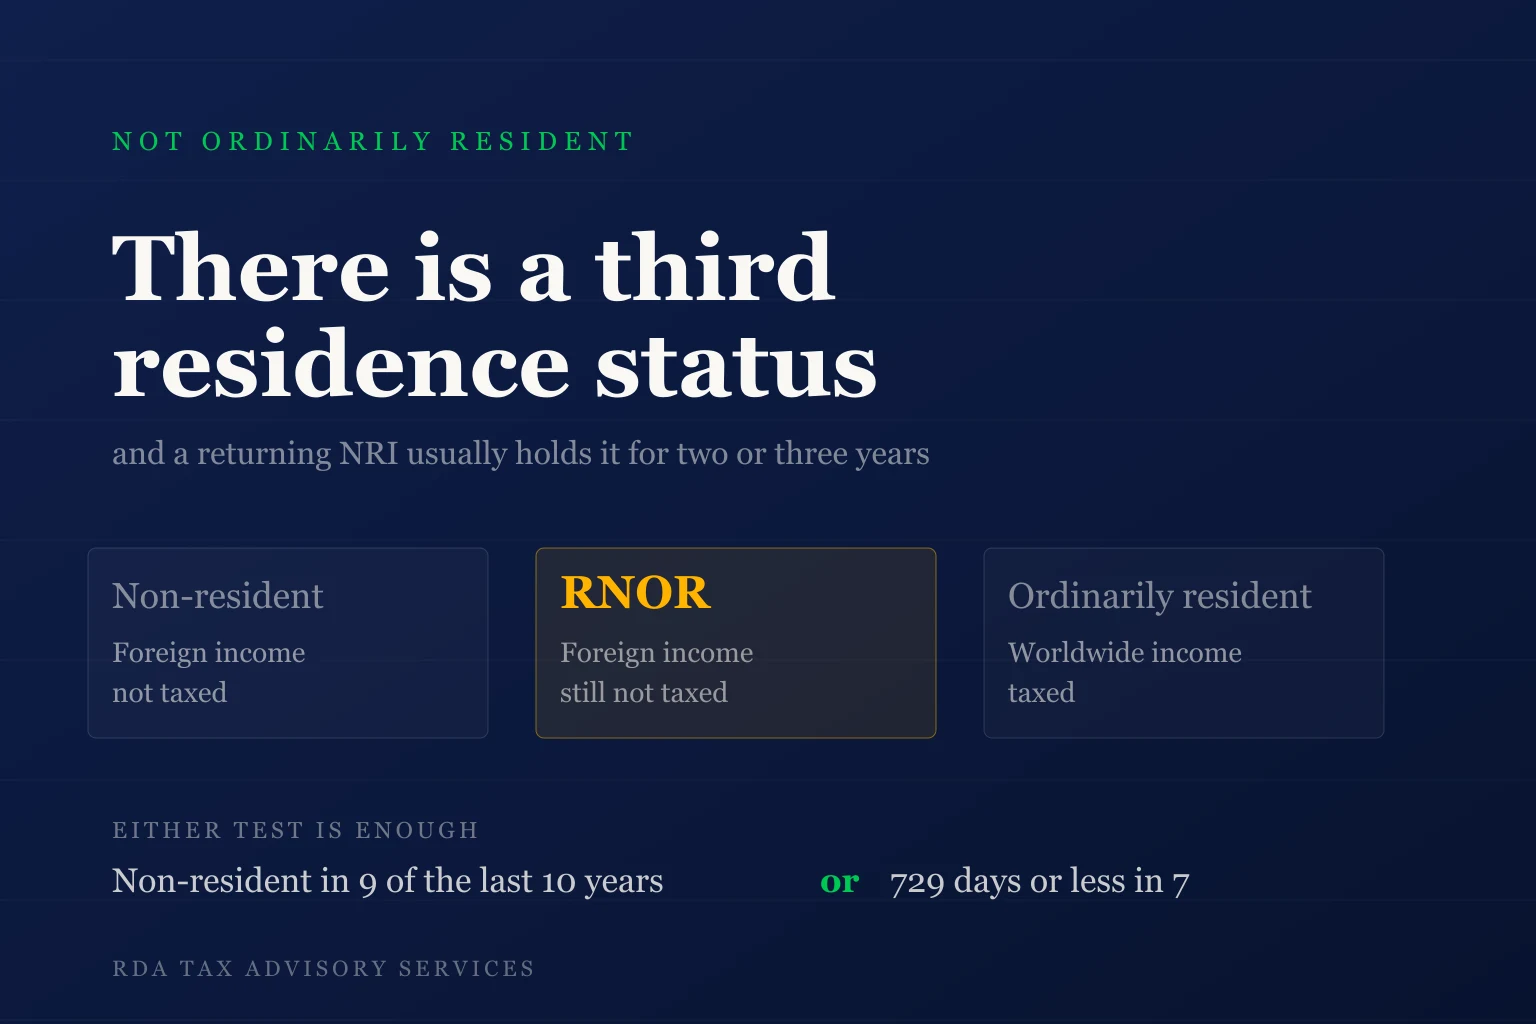
Indian tax residence is not a binary. Not ordinarily resident sits between the two, keeps foreign income outside the Indian net, and usually lasts two or three years after a return to India. Either of two tests gets you there — and most people only know about one of them.
CA Rahul Dang
Founder & Practice Lead
Most people believe Indian tax residence has two settings: resident, or non-resident. There is a third, and for someone moving back to India after years abroad it is usually the most valuable status they will ever hold.
It is called not ordinarily resident — RNOR. It is a resident status, but with the tax scope of something much closer to a non-resident, and it typically lasts two to three years after a return to India. A great many returning NRIs pay tax on foreign income during years in which they were not required to.
Two questions, in order
The test runs in sequence and the order matters.
Are you resident in India at all? Section 6(1) of the 1961 Act: you are resident if you are in India for 182 days or more in the year, or if you were in India for 365 days or more across the four preceding years and 60 days or more in the current year.
If you are resident, are youordinarilyresident? That is the second test, and it is where RNOR lives.
A non-resident never reaches question two. RNOR is a sub-category of resident, not an alternative to it.
Two softeners sit inside question one, in Explanation 1 to section 6(1). For an Indian citizen who leaves India for employment outside India, or as a member of the crew of an Indian ship, the 60-day limb reads 182 days instead. For an Indian citizen or person of Indian origin visiting India, the 60-day limb also reads 182 days — but only 120 days where total income other than income from foreign sources exceeds ₹15 lakh in that year.
How you become RNOR
Section 6(6) of the 1961 Act, and section 6(13) of the 2025 Act, set out the routes. For an individual, the two that matter in practice are:
Route
Test
A
You were a non-resident in nine out of the ten years preceding that year
B
You were in India for 729 days or less across the seven years preceding that year
Either one is enough. The statute says “or”. You do not have to satisfy both, and this is the single most common misunderstanding about the status.
729 days across seven years is an average of a little over 104 days a year — so someone who came back to see family for three or four months annually can still be comfortably inside route B.
The same two tests apply to a Hindu undivided family, by reference to the position of its manager — section 6(6)(b) of the 1961 Act, and section 6(13)(a) of the 2025 Act, which merges the individual and HUF limbs into a single clause.
There are two further routes, both aimed at high earners rather than ordinary returnees:
An Indian citizen or person of Indian origin with total income other than foreign-source income above ₹15 lakh who is in India for 120 days or more but less than 182 days — section 6(6)(c); section 6(13)(b).
An Indian citizen who is deemed resident — section 6(6)(d); section 6(13)(c). The deeming provision, section 6(1A) of the 1961 Act, catches an Indian citizen with non-foreign-source income above ₹15 lakh who “is not liable to tax in any other country or territory by reason of his domicile or residence or any other criteria of similar nature”. Someone caught by it is deemed resident but is RNOR, not ordinarily resident.
Why the status is worth so much
Everything turns on section 5, which fixes the scope of total income.
For an ordinarily resident, section 5(1) brings in worldwide income — including, under clause (c), income which “accrues or arises to him outside India”.
The proviso to section 5(1) carves RNOR out of exactly that clause:
“Provided that, in the case of a person not ordinarily resident in India …, the income which accrues or arises to him outside India shall not be so included unless it is derived from a business controlled in or a profession set up in India.”
Section 5(1)(c) of the 2025 Act says the same thing in a single sentence: where the person is not ordinarily resident, foreign-accruing income “shall be included only when it is derived from a business controlled in or a profession set up in India”.
So for the two or three years the status lasts, foreign income generally stays outside the Indian net.
Income
Non-resident
RNOR
Ordinarily resident
Received or deemed received in India
Taxed
Taxed
Taxed
Accrues or deemed to accrue in India
Taxed
Taxed
Taxed
Accrues outside India — ordinary case
Not taxed
Not taxed
Taxed
Accrues outside India, from a business controlled in or profession set up in India
Not taxed
Taxed
Taxed
Read the last row carefully — it is the only line on which an RNOR is worse off than a non-resident, and it is the one that catches people who return to India and keep running an overseas business from here. “Controlled in India” is about where control is exercised, not where the entity is registered. If you come back and start directing a foreign business from Pune, that income can come into charge even while you are RNOR.
What this looks like in practice
Take someone who worked abroad for eight years and returns to India permanently in, say, the middle of a financial year.
In the year of return they may well be non-resident outright, if they are in India for less than the applicable day threshold.
In the following years they become resident on day count — but having been non-resident in nine of the ten preceding years, or having spent 729 days or less in India over the preceding seven, they are RNOR.
Once neither route is satisfied any longer, they become ordinarily resident, and worldwide income comes into charge.
That middle band is usually two to three years, and it is a planning window rather than a loophole: it is the period in which foreign income can be realised, overseas accounts restructured, and foreign assets repositioned at a materially lower Indian tax cost. The decisions are much cheaper to make inside the window than after it closes.
Count the days properly and keep the evidence. Both routes are arithmetic, and the arithmetic reaches back seven or ten years. Passport stamps, boarding passes and entry and exit records are what prove the position if it is ever questioned — and by the time it is questioned, the years in question are long past.
One thing this guide does not answer
Residential status and reporting obligations are two different questions. Whether, and to what extent, an RNOR must disclose foreign assets and foreign income in the return is governed by the return forms and the rules rather than by sections 5 and 6, and we have not set that out here. Do not assume that a favourable scope of charge also removes a disclosure obligation — the penalties attached to non-disclosure of foreign assets are severe and sit under a separate law. Check the reporting position for your year separately. Our guides to Schedule FA disclosure and the FAST-DS scheme are the place to start, and this is a question worth taking advice on rather than inferring.
Which Act applies to your year
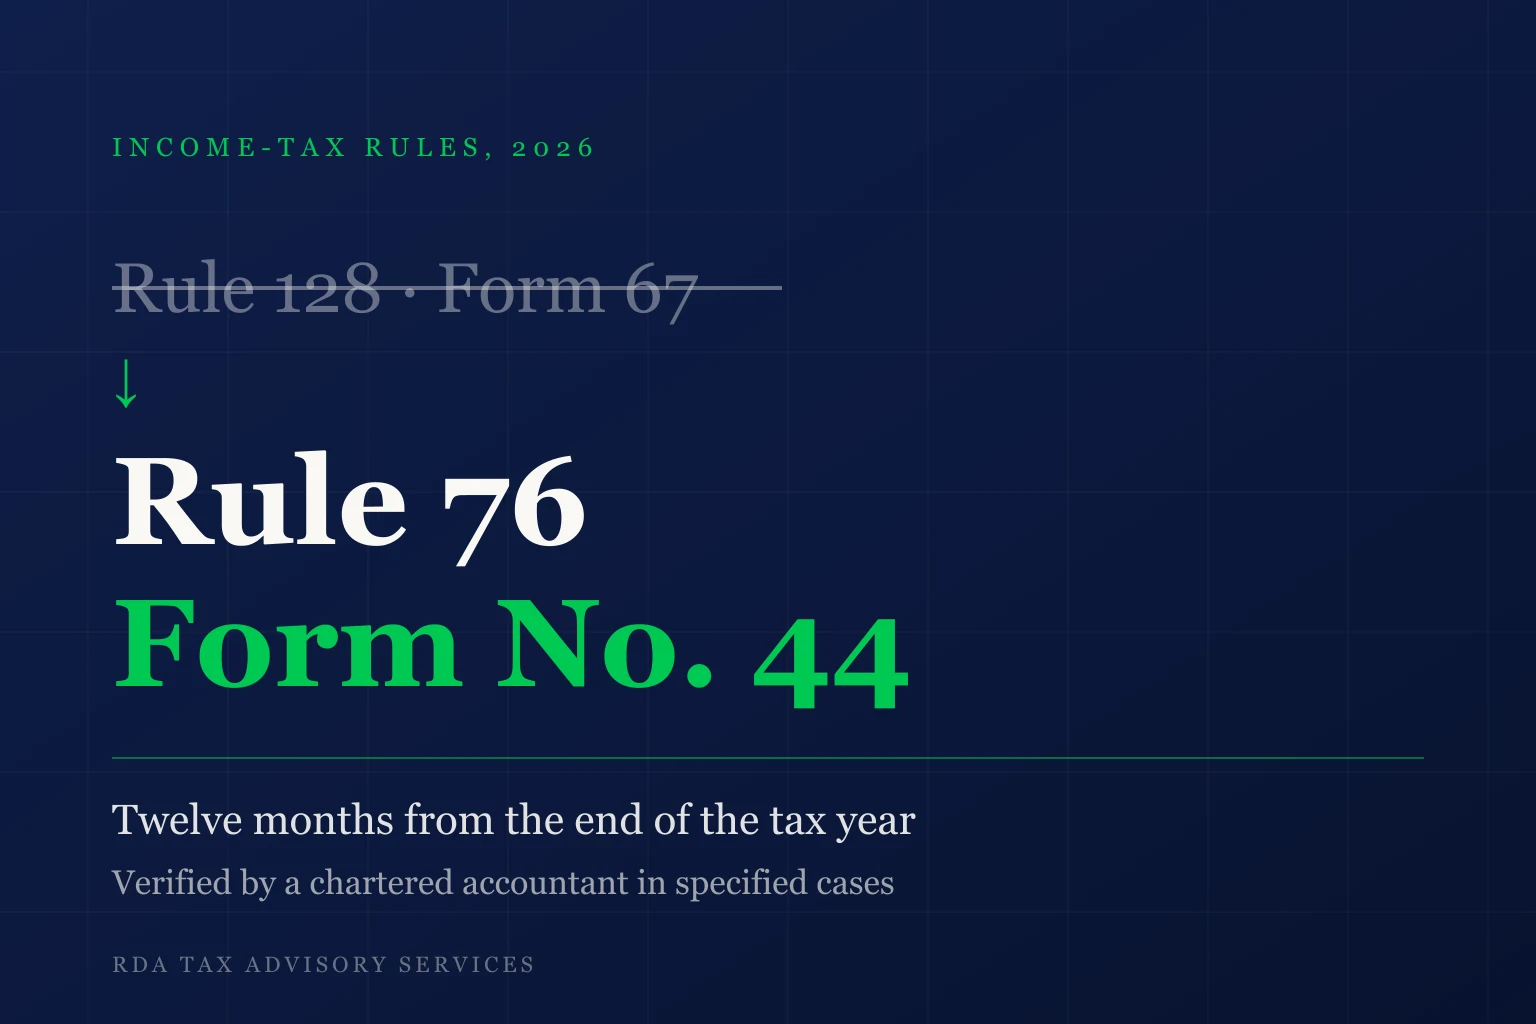
Section 536(2)(c) of the Income-tax Act, 2025 continues the 1961 Act for proceedings in respect of any tax year beginning before 1 April 2026. So FY 2025-26 and earlier run on sections 5 and 6(6) of the 1961 Act; tax year 2026-27 onwards runs on sections 5 and 6(13) of the 2025 Act.
The substance is carried across without change on the points that matter here: the same two routes, the same 729-day and nine-out-of-ten tests, the same ₹15 lakh and 120-day limbs, and the same carve-out in section 5 for foreign income other than from a business controlled in or profession set up in India. The 2025 Act reorganises the clauses — the individual and HUF limbs are merged, and the definition of income from foreign sources moves to section 6(14) — but the tests themselves are the same.
Checklist for a returning NRI
Settle the day count first for the year in question, including the Explanation 1 softeners if you left for employment abroad or are visiting India.
If you are resident, test both RNOR routes — nine out of ten years non-resident, or 729 days or less over seven years. Either will do.
Work out when the window closes. It is predictable years in advance, which is what makes it plannable.
Identify any foreign income that would be caught anyway — anything from a business controlled in India or a profession set up in India.
Sequence the decisions inside the window, not after it.
Keep the travel evidence. Seven and ten year look-backs need records you will not be able to reconstruct later.
Check the reporting position separately from the charging position.
We advise returning NRIs in Pune and across India on exactly this: establishing the status year by year, working out when the RNOR window opens and closes, and sequencing the realisation of foreign income and the restructuring of overseas holdings inside it. The window is short and it does not reopen. The right time to look at it is before the move, not after the second year.
Sources
Income-tax Act, 1961 — section 5 with the proviso to sub-section (1), and section 6(1) with Explanation 1, section 6(1A) and section 6(6) with its Explanation, read from the Income Tax Department’s consolidated text, pages 18 to 22. Official text, section by section
Income-tax Act, 2025, as amended by the Finance Act, 2026 — section 5, and sections 6(12), 6(13) and 6(14), pages 27 to 30. Official text, section by section
This guide explains the statutory tests for not-ordinarily-resident status and the scope of income that follows from it. It is not advice on any particular case, and it deliberately does not address foreign-asset reporting obligations, which are governed separately. Residential status turns on day counts across several years and on the facts of a particular move. Take advice on your own position before relying on the status.
Common questions
Frequently asked.
What is RNOR status?
Not ordinarily resident is a sub-category of resident. You first test whether you are resident at all under section 6(1); if you are, you then test whether you are ordinarily resident. An RNOR is a resident whose foreign-accruing income is still largely outside the Indian tax net, because the proviso to section 5(1) of the 1961 Act — and section 5(1)(c) of the 2025 Act — excludes it unless it is derived from a business controlled in or a profession set up in India.
How do I qualify as RNOR?
Either of two tests, and only one is needed. You were a non-resident in India in nine out of the ten years preceding that year; OR you were in India for 729 days or less across the seven years preceding that year. The statute says or — section 6(6)(a) of the 1961 Act, section 6(13)(a) of the 2025 Act. 729 days over seven years is an average of just over 104 days a year, so regular family visits do not necessarily take you out of it.
How long does RNOR status last?
Typically two to three years after a permanent return to India. It is not a fixed statutory period — it is simply how the day-count tests play out. Once neither the nine-out-of-ten test nor the 729-day test is satisfied any longer, you become ordinarily resident and worldwide income comes into charge. Because both tests look backwards over fixed periods, the closing date is predictable years in advance.
Is foreign income taxed for an RNOR?
Generally no, with one important exception. The proviso to section 5(1) of the 1961 Act excludes income accruing outside India from an RNOR total income UNLESS it is derived from a business controlled in or a profession set up in India. So if you return to India and direct an overseas business from here, that income can be charged even while you are RNOR. Control is about where it is exercised, not where the entity is registered.
Can an HUF be RNOR?
Yes. The same two tests apply to a Hindu undivided family by reference to the position of its manager — section 6(6)(b) of the 1961 Act. The 2025 Act merges the individual and HUF limbs into a single clause, section 6(13)(a), but the tests are the same.
Does the ₹15 lakh rule affect RNOR?
Yes, through two further routes. An Indian citizen or person of Indian origin with total income other than foreign-source income above ₹15 lakh who is in India for 120 days or more but less than 182 days is RNOR — section 6(6)(c), section 6(13)(b). And an Indian citizen deemed resident under section 6(1A), which catches someone with non-foreign-source income above ₹15 lakh who is not liable to tax in any other country by reason of domicile, residence or similar criteria, is RNOR rather than ordinarily resident — section 6(6)(d).
Does RNOR status remove foreign asset reporting obligations?
Do not assume so. Residential status and reporting are separate questions. The scope of charge is fixed by sections 5 and 6, but what must be disclosed in the return is governed by the return forms and the rules, and this guide deliberately does not state that position. The penalties for non-disclosure of foreign assets are severe and sit under a separate law, so check the reporting position for your year independently and take advice rather than inferring it from the charging position.
Which Act applies to my residential status?
Section 536(2)(c) of the Income-tax Act, 2025 continues the 1961 Act for proceedings in respect of any tax year beginning before 1 April 2026. FY 2025-26 and earlier run on sections 5 and 6(6) of the 1961 Act; tax year 2026-27 onwards runs on sections 5 and 6(13) of the 2025 Act. The substance is carried across unchanged on every point that matters here.